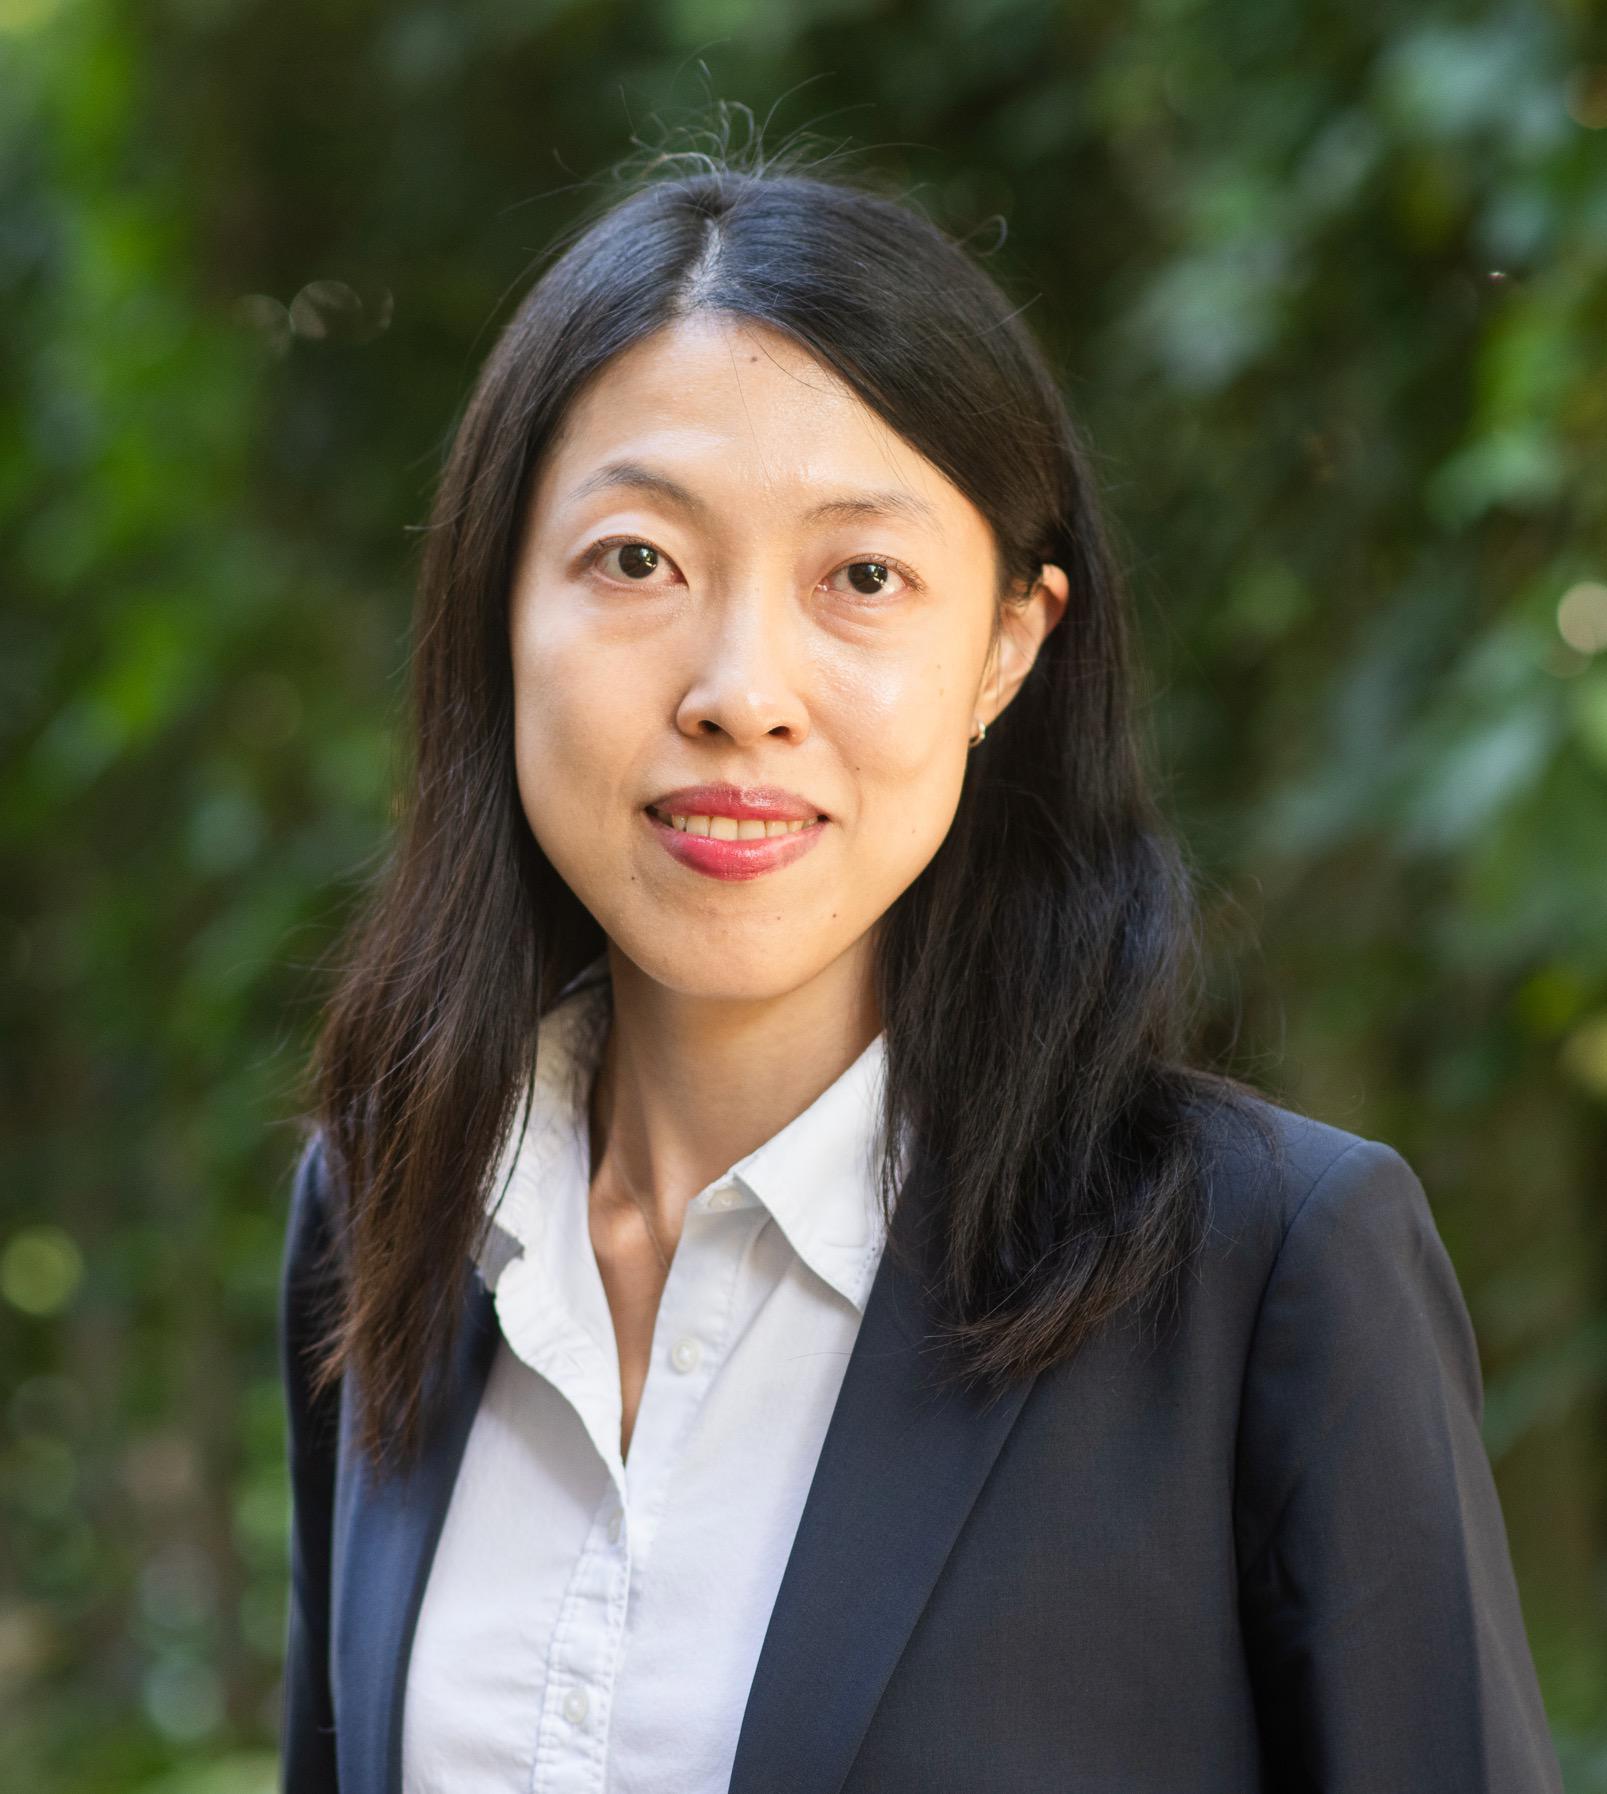
Hello! Welcome to my homepage.
I am a financial economist at the University of Melbourne. I study asset pricing and optimal risk-sharing. My current projects investigate risk-sharing and risk transmission across investor types and capital markets.
Download my résumé.
Interests
- Asset Pricing
- International Finance
- Credit Risk
- Financial Institutions
- Sustainable Finance
Education
PhD in Finance, 2023
McGill University
MSc in Finance and Economics, 2015
London School of Economics
BA in Economics, 2014
Fudan University
Research
Publications
Excess Co-movement in Default Risk
This paper proposes a new explanation for the excess co-movement in default risk observed across borrowers. We develop a model with endogenous default decisions in a multi-borrower economy, where a negative idiosyncratic shock to one borrower reduces its creditworthiness while simultaneously increasing the relative importance of another borrower. The resulting increase in systematic risk raises the borrowing costs of the latter, accelerating its default decision, particularly when short-term refinancing is required. This mechanism uncovers a novel source of default risk dependence that cannot be attributed to shared fundamental shocks alone. Moreover, the embedded leverage in equity enables our model to jointly explain excess co-movement in default probabilities, credit spreads, equity returns, and equity volatilities, aligning with recent empirical evidence across U.S. industries.
Nature Risk Management in Domestic and Foreign Institutional Investments
We compare nature risk management in domestic and foreign institutional investments using a comprehensive global sample of firms covered by the S&P nature risk and FactSet ownership datasets. Physical risk and biodiversity risk negatively predict domestic and foreign institutional ownership at the firm level. At the institution-firm level, institutions avoid firms with high physical risk exposure more in domestic investments compared to foreign ones, possibly because of a higher perception or easier assessment of domestic physical risks. Conversely, institutions tilt toward high-biodiversity-dependency firms in their domestic portfolios while avoiding similar firms in their foreign ones, indicating a preference for engagement at home and divestment abroad. These differences in nature risk management between domestic and foreign investments cannot be explained by differences in risk-adjusted returns.
Working Papers
Institutional Investment and International Risk-sharing
This paper proposes a new channel for local risk premia in international stocks based on investor underdiversification. Holdings data reveal two facts. First, retail investors display near-perfect home bias while institutions are globally diversified. Second, institutions substantially underdiversify within each market. Institutions' imperfect cross-market hedging generates an institutional local premium, while their limited investment scope leaves residual risk, generating a retail local premium. These premia average 2.2% and 2.5% across 21 developed markets and 3.5% and 4.5% across 20 emerging markets. Unlike the investability channel, local risk premia persist even when markets are fully open to foreign investors.
Ownership Structure and Short Selling Around the World
We study how ownership structure affects equity lending, short selling, and price efficiency in 40 markets globally. Non-institutional block ownership reduces lending supply, whereas foreign institutional ownership increases it, with a larger effect than domestic institutions. Among institutions, passive and index investors play a particularly large role. We establish causality by exploiting MSCI index additions as plausibly exogenous shocks to ownership structure. Stocks whose ownership facilitates lending also have broader coverage by lending agents and prime brokers, consistent with intermediary connections being a key channel. Such ownership structure translates into greater short-selling activity and more efficient prices.
Sustainable Investing Home and Abroad
We study how firm ESG performance affects domestic and foreign institutional investments. At the firm level, the marginal effects of ESG on institutional ownership vary across institution origin and investment destination countries. At the institution-firm level, institutions tilt towards high-ESG firms only when they are domestic. We term this asymmetry in ESG preference between domestic and foreign investment the “ESG home bias”. We explore ESG information environment, country E&S awareness, and ESG factor discount as potential economic mechanisms and find that the ESG home bias reflects a combination of these factors, the most important being information asymmetry about the ESG outcome measured by ESG uncertainty.
Who Invests in What? Public Firms Ownership Around the World
We construct a comprehensive database of public firm ownership in 49 countries and study the investment scope and preferences of different types of investors. Aggregate home bias has declined but is still much higher in emerging markets (EMs). Institutions have become more globally diversified but invest in a limited number of stocks. Retail investors remain highly home-biased. Institutions of different domiciles and types continue to show a strong preference for larger, more liquid, and more visible firms in both pooled regressions and country-level analyses but exhibit considerably heterogeneous preferences for other firm characteristics. Retail investors are mostly present in small and illiquid firms.
Code
FactSet Holdings and Ownership
Aggregate FactSet 13F and fund holdings at the institution level and compute portfolio characteristics and security- and firm-level ownership, following Ferreira and Matos (JFE, 2008).
Sustainalytics via Morningstar
Download Sustainalytics ESG ratings via the Morningstar Direct Excel add-in.
Global individual stock data retrieval Datastream
Filter the Datastream global equity universe and auto-update DFO request tables, following Griffin, Kelly and Nardari (RFS, 2010) and Chaieb, Langlois and Scaillet (JFE, 2021).
Individual stock returns Compustat Global
Build monthly USD returns for individual stocks in the Compustat Global universe, following the filters and cleaning of Chaieb, Langlois and Scaillet (JFE, 2021).
Teaching
- Empirical Asset Pricing (PhD), Instructor, 2026 S1, Melbourne
- International Financial Management (Master’s), Instructor, 2024-2026 S1, Melbourne
- Investments (undergraduate), Instructor, 2022 Summer (course outline, evaluation), McGill
- Investments & Portfolio Management (MBA), TA, 2022 Winter, McGill
- Investments (undergraduate), Instructor , 2020 Summer (evaluation), McGill
- Financial Derivatives (undergraduate), TA, 2018 Winter (evaluation), McGill